The new financial year has opened with a strong regulatory focus on investor outcomes, transparency and good conduct. Recent Financial Markets Authority (FMA) engagement on performance advertising has reinforced the importance of balanced communications, while a series of reports and reviews released over recent months offer valuable indicators of the regulator’s current areas of interest. Together, they provide a useful snapshot of the key issues facing the industry as FY27 begins.
Performance advertising still under the microscope
Recent FMA engagement on performance advertising has reinforced that advertisements must give investors a balanced overall impression. Performance should not dominate the message or be presented over a single, selectively chosen period, known as cherry picking, without appropriate context, particularly where that period is shorter than the fund’s recommended minimum investment timeframe. Advertisements should be able to stand on their own, clearly identifying the performance period and source, providing meaningful comparisons and balancing performance with other relevant factors such as risk, fees etc. Managers are also expected to have robust approval processes that bring genuine legal and compliance challenge, document their rationale for key decisions and test the impression an investor is likely to take from the advertisement.
KiwiSaver Annual Report – FUM reaches a record $138.8 billion
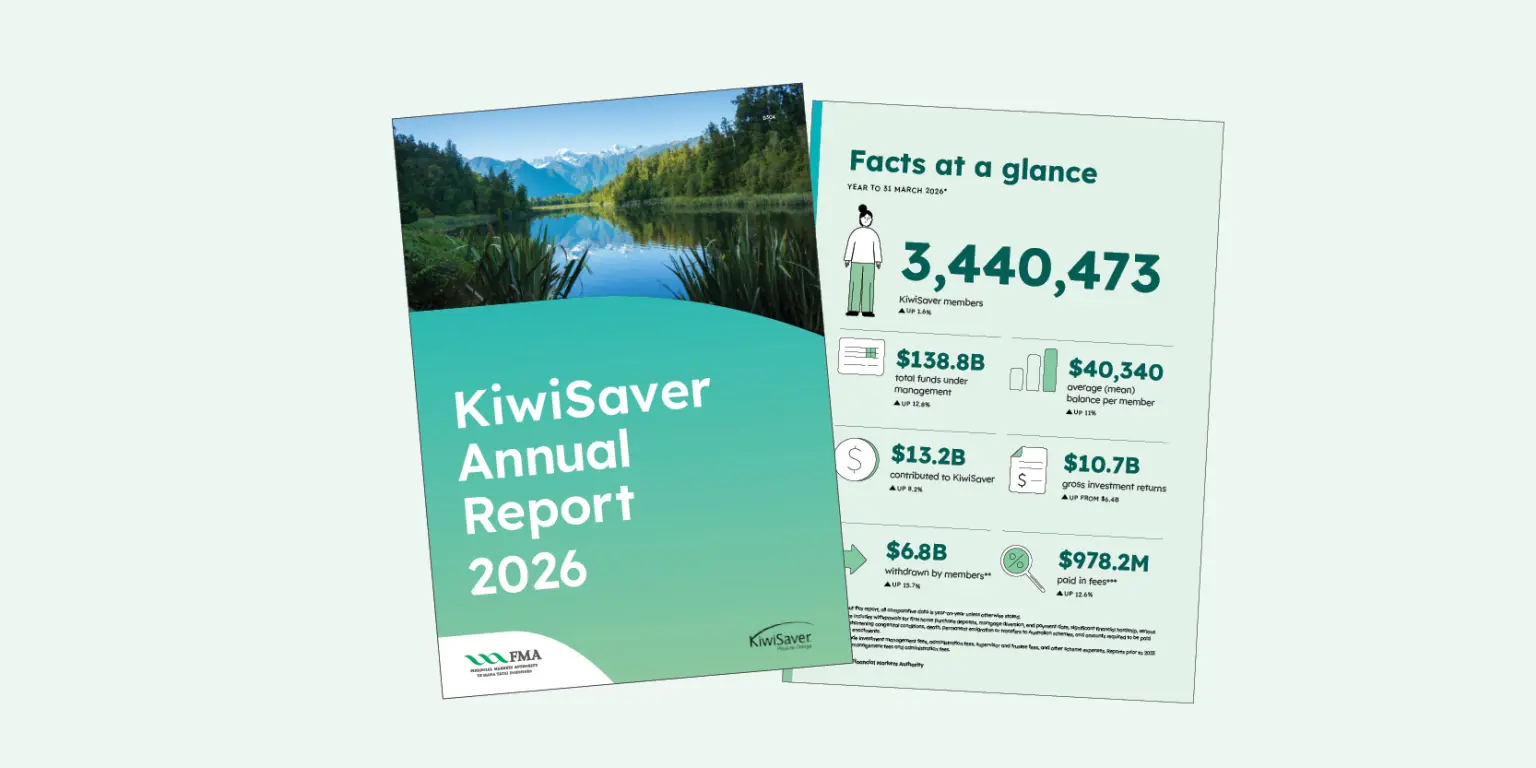
In the new KiwiSaver Annual Report, the FMA reported funds under management (FUM) grew 12.8% across the KiwiSaver market reaching a record $138.8 billion, and member numbers grew by 1.6% to 3.44 million members. The average member balance has reached a new average high of $40k. Increases in withdrawals were also reported to be up by 15.7% with a total across all categories at $6.8 billion for the year. This included $3.3 billion by those aged over 65, and $531.5 million in significant financial hardship withdrawals.
Financial Conduct Report: Outlining regulatory priorities
The FMA released its second annual Financial Conduct Report, with a move towards a sector focused approach, with several cross-sector themes. These themes include managing conflicts from remuneration structures, product design for new and redesigned products, complaints, including how complaints are handled and how data drives improvements, and fraud detection and prevention.
Work continues on related party transactions
The FMA continues to finalise its insights paper on related party transactions, with ongoing industry and supervisor engagement. Separately, the FMA published a report on related party disclosures in financial statements by MIS managers and investment schemes in August. This report followed a review of 61 MIS managers and schemes by the FMA. It reported that while most managers were identifying and disclosing related party relationships and transactions, the disclosures often lacked enough detail for users to fully understand their nature, extent and potential impact.
FMA’s Effective Protection of Client Assets report
The FMA released its second Effective Protection of Client Assets report, a timely publication for DIMS, financial advice providers and firms involved in custody arrangements. The FMA's primary concern is not whether custody is outsourced, but whether licensed providers can demonstrate effective oversight, governance, reporting and protection of client assets.
Most providers met basic custody obligations, but the FMA identified weaknesses in oversight, governance, reporting and investor understanding of how assets are protected.
When it comes to outsourcing, licensed providers remain accountable for client asset protection and must actively oversee custodians, assurance reports, reconciliations and service performance.
The report found custody reporting controls are often inadequate. Many can’t reliably demonstrate that custody reports are delivered to and received by investors, reducing an important safeguard against errors and fraud.
The FMA shared that governance and fraud controls need strengthening. Common weaknesses included poor segregation of duties, weak verification of withdrawal and account change requests, limited incident management and insufficient control testing.
Fee and custody disclosures are often too complex or unclear, the FMA said. Investors frequently lack a clear understanding of custody fees, related charges and how their assets are held and safeguarded. The FMA expects greater transparency and investor education.